 AVNews24Desk
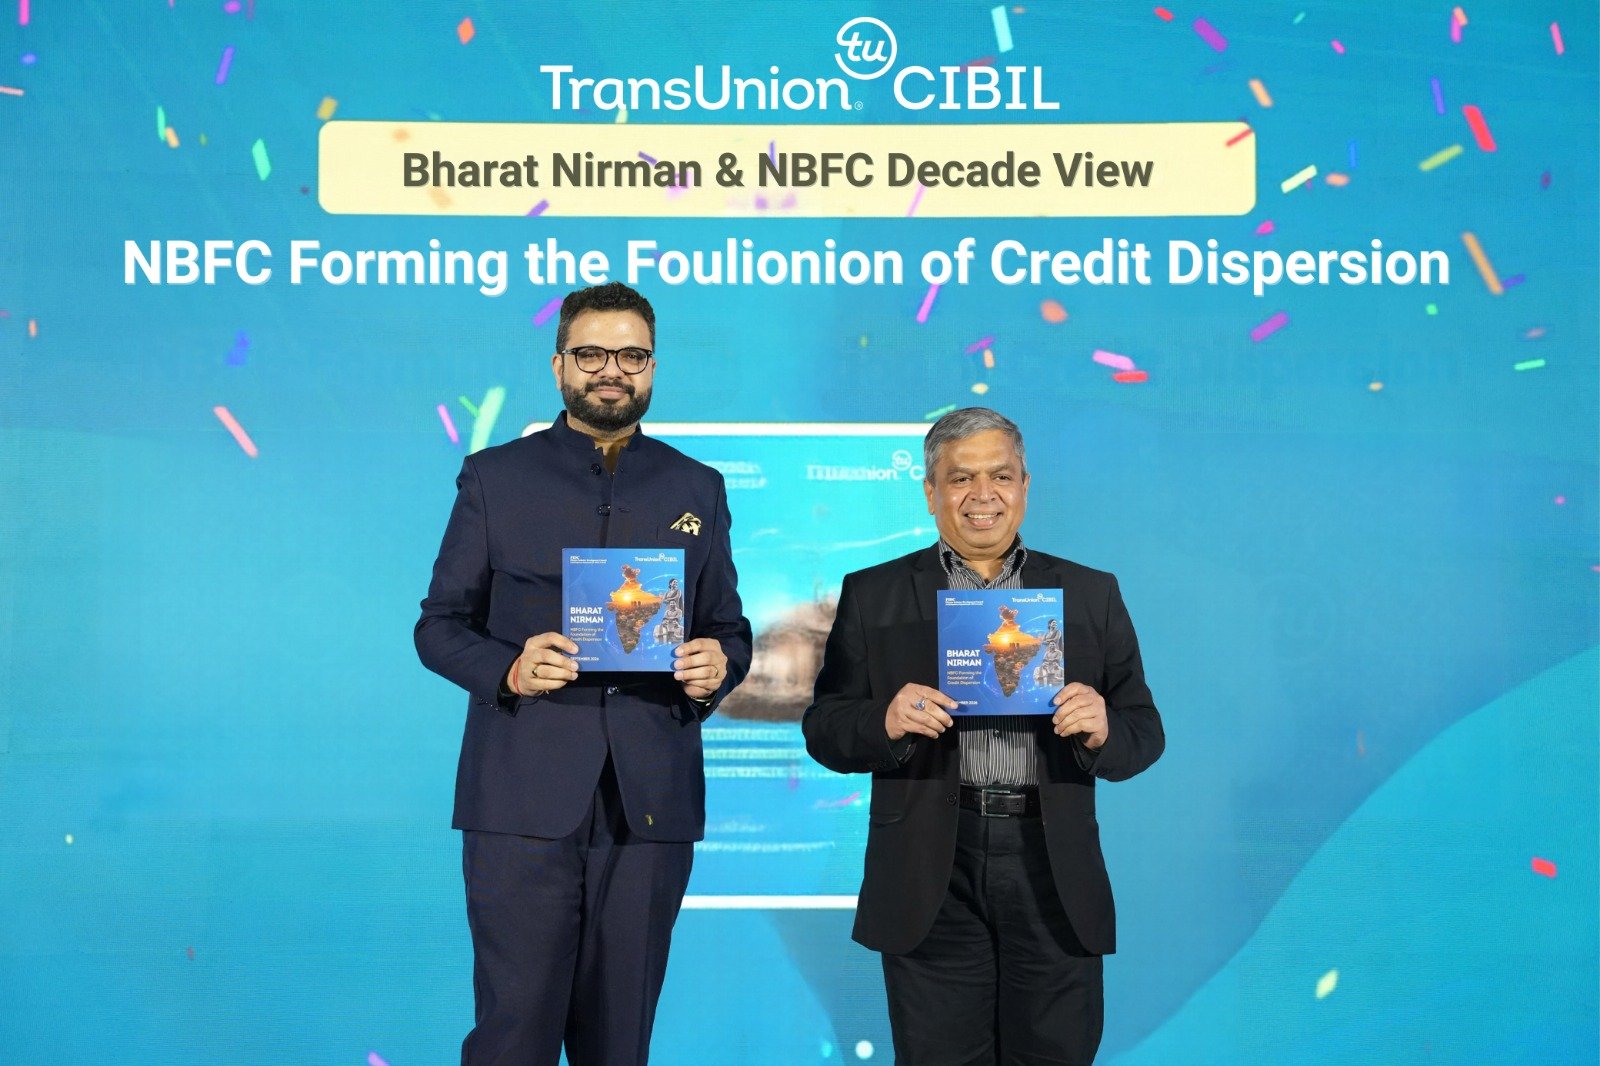
Mumbai: Non-Banking Financial Companies (NBFCs) are playing an increasingly important role in expanding access to formal credit in India. According to a joint report by the Finance Industry Development Council (FIDC) and TransUnion CIBIL, NBFCs accounted for 47% of New-to-Credit (NTC) consumer loan originations as of June 2026.
The report, Bharat Nirman: NBFC Forming the Foundation of Credit Dispersion, said 36% of credit-eligible consumers have accessed credit through an NBFC, while 46% of all credit-active consumers currently have an NBFC loan.
Over the last decade, the credit-active consumer base of NBFCs has grown nearly seven times. Their share of retail loan originations also increased from 33% in June 2016 to 43% in June 2026. However, their share of first-time borrowers declined from 28% to 16% during the same period, showing a growing focus on consumers who already have a credit history.
NBFCs have a strong presence in small-ticket lending. Loans of up to ₹2 lakh account for 82% of consumer credit originations by volume, with NBFCs contributing 47% of these loans, compared with 17% by banks.
Their reach has also expanded in smaller cities and rural areas. The share of semi-urban and rural consumers in the NBFC credit-active base increased from 31% in 2016 to 59% in 2026. Women’s share rose from 18% to 27%.
The report also highlighted improving portfolio quality. The share of above-prime consumers increased from 24% in June 2019 to 32% in June 2026, while 90-plus-day delinquency fell from 2.7% to 1.1%.
NBFCs are also expanding in commercial lending. Their share of credit-active commercial entities rose from 10% in 2021 to 18% in 2026, indicating a growing role in financing businesses alongside consumers.